Effectively navigating your personal tax approach, private wealth strategies and other complexities of your affairs while you’re still alive is essential to safeguard your legacy.
Table of Contents
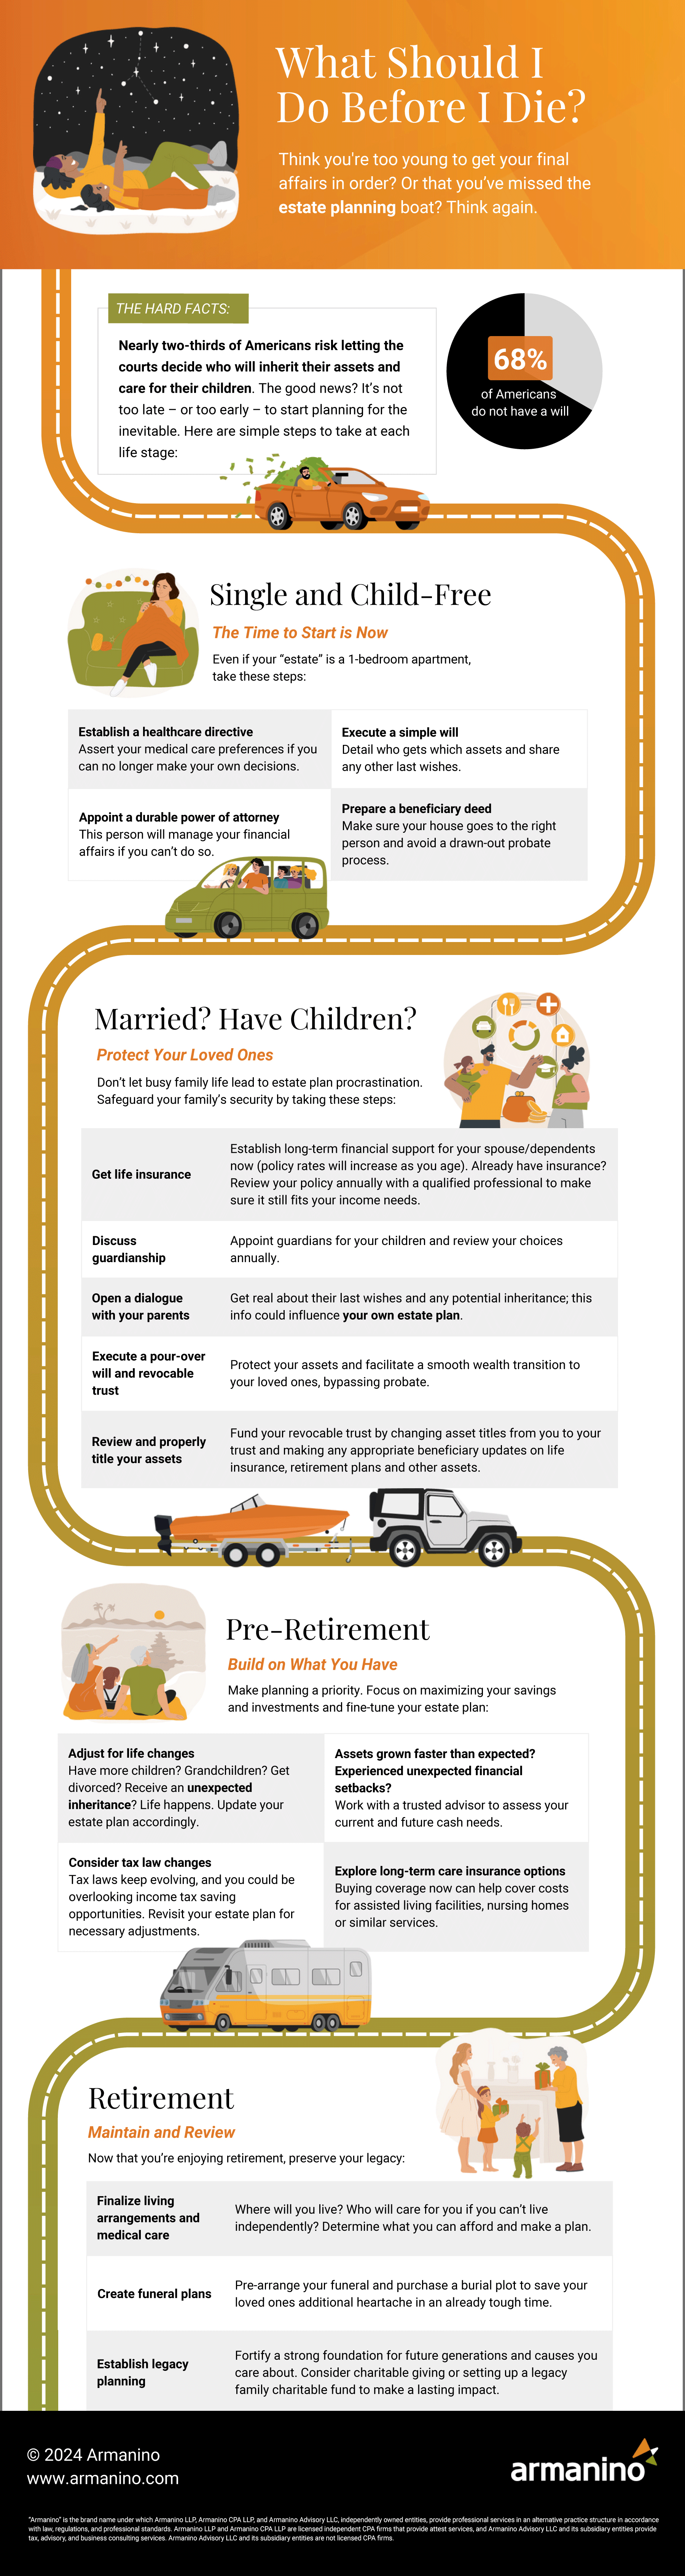
Want to display this infographic on your site? Copy and paste the following code. Be sure to include attribution to armanino.com with this graphic.
If you have a substantial estate, IRS Form 706 is crucial to your planning. It serves as a gatekeeper to make sure your hard-earned assets are properly accounted for and protected.
Though Form 706 would typically be filed after your death, ignoring it’s intricacies now could be a costly mistake. The One Big Beautiful Bill Act (OBBBA) made today’s lifetime estate and gift tax exemption thresholds permanent. The thresholds are $15 million per person in 2026, with annual inflation adjustments beginning in 2027.
By delving into the details now, you’ll get the relief of knowing that you’ve made informed use of your available exemption and considered available tax-planning opportunities — all while laying the foundation for a comprehensive estate plan that preserves your legacy, provides a smooth transition for your loved ones and withstands the test of time.
Here’s a breakdown of what you need to know about Form 706 and how you can use it to help prepare your estate.
Form 706, officially known as the United States Estate (and Generation-Skipping Transfer) Tax Return, provides a comprehensive overview of an estate’s financial status and reports the value of the deceased person’s estate at the time of their death.
Filing this form is necessary to accurately determine the estate’s worth and to calculate any estate tax liabilities that may be owed. Filing Form 706 is often a requirement under federal estate tax rules.
There are two types of Form 706 returns: the required form and the portability form:
Your executor or personal representative is responsible for filing Form 706. Generally, this task is handled by your accountant or family attorney, depending on their capabilities and the specific estate needs. The important takeaway is to assign someone with specific experience preparing returns such as Form 706 rather than professionals whose background is in income tax filings.
The filing deadline for Form 706 is usually nine months following the individual’s death. If filers need more time, they can request a six-month extension using IRS Form 4768.
Though Form 706 is filed after your death, considering it now can influence your estate planning approach. Being proactive allows you and your loved ones to better preserve wealth, avoid missed opportunities and minimize potential tax burdens.
Don’t wait to have estate planning discussions with your family and advisors. While the OBBBA ended years of uncertainty over the scheduled 2026 “sunset,” it does not eliminate the need to plan.
For instance, your assets may appreciate past the exemption, future legislation can alter the rules and some states may impose their own estate or inheritance taxes at much lower thresholds. Making preparations now and keeping the conversation open can help you spare your loved ones unwelcome surprises and protect your legacy.
Form 706 plays several crucial roles in your estate planning.
Filing Form 706 helps keep your estate compliant with IRS regulations. According to recent IRS data, the overall audit rate for Form 706 is about 7%, compared with a typical income tax return audit rate of around 1%. Twenty-two percent of estates larger than $10 million get audited; estates greater than $100 million get audited about 50% of the time.
If your estate is large and contains hard-to-value assets, such as closely-held business interests, real estate, art and collectibles, well-supported valuations and complete documentation are your best defense against scrutiny.
Use Form 706 to catalog your assets, liabilities and lifetime gifts, including real estate, investments, business interests and personal property. This form helps determine whether your estate is subject to federal estate tax and, if so, the potential liabilities. Anticipating these challenges now helps you strengthen your estate planning strategy and pave a clear path forward for your heirs.
Form 706 can serve as a blueprint for proactive tax planning. High-net-worth individuals and their advisors can strategically minimize estate tax liabilities using strategies such as annual exclusion gifts, the federal estate tax marital deduction, charitable deductions, intentionally defective grantor trusts (IDGTs) and qualified disclaimers.
Intentionally defective grantor trusts. A properly structured IDGT can remove transferred assets and their future appreciation from your taxable estate while allowing you to continue paying the income tax on the trust’s earnings. Those tax payments can further reduce your taxable estate without being treated as additional gifts to the trust.
However, assets excluded from your estate don’t generally receive a step-up in basis at your death, which can create a trade-off between estate and income tax planning.
Qualified disclaimers. A beneficiary can use a qualified disclaimer to decline an inheritance, allowing the interest to pass under the governing instrument or applicable law without being treated as a taxable gift by the person disclaiming. Building disclaimer options into your plan gives your family flexibility after your death, such as allowing assets to pass to a family trust.
A qualified disclaimer generally must be irrevocable and unqualified, made in writing within the applicable nine-month period, delivered to the appropriate person, made before the beneficiary accepts the property or its benefits and cause the property to pass without direction by the disclaiming beneficiary. The nine-month period generally runs from the later of the transfer creating the interest or the beneficiary reaching age 21.
A complete view of your assets is essential to properly file Form 706 and stay on top of your estate plan. To prepare to file Form 706, your executor/personal representative must compile comprehensive documentation of your estate’s assets and liabilities. This typically includes individually owned property, jointly owned property, revocable living trusts, life insurance and community property. This organized record not only facilitates estate tax compliance but also simplifies the settlement of the estate for heirs and executors by providing a clear overview of your financial affairs.
The generation-skipping transfer tax (GST tax) can apply to certain transfers to “skip persons,” generally individuals two or more generations below the transferor, such as grandchildren, as well as certain trusts, who would receive an inheritance.
It can arise through direct skips, taxable distributions and taxable terminations. Because the tax is designed to prevent individuals from avoiding transfer tax at an intervening generation, the rules governing exemptions, allocations and generation assignments are intricate. Careful planning helps keep wealth transfer strategies aligned with your estate planning goals.
For 2026, the GST tax exemption is $15 million per person, matching the estate and gift tax basic exclusion amount. GST transfers that are not fully protected by allocated GST exemption can be subject to GST tax at a rate of up to 40%. Unlike the estate and gift tax exclusion, unused GST tax exemption is not portable to a surviving spouse, so it should be allocated deliberately during lifetime or at death.
To begin preparing for a Form 706 filing, conduct a “state of your estate” analysis:
Evaluating your estate early and keeping your advisors and loved ones informed as changes occur, helps you identify potential issues and get maximum value from your estate planning.
Challenges such as difficult-to-value assets, complex tax laws and the inherent difficulty of thinking about your demise can make estate planning feel overwhelming at any age. Find out how our compassionate trust and estate planning tax consultants can help you create a personalized estate strategy that builds and preserves your legacy.
Toolkit
Looking for a caring resource to help loved ones close out your final affairs? Download our What to Do When I Die checklist and documents toolkit.